Very few people go out and look for a financial adviser. You only do it when you’re in a position where you have to. A redundancy, an inheritance, a pension that’s just been sitting there for 15 years, or that life policy your partner took out in 2009 which has never been looked at since. It’s not a decision you normally make in a cool, rational way and that’s why the quality of the advice you get at that moment is so critical.
The advice market in Ireland has changed massively over the last 10 years or so. There’s a lot more choice now, a lot more apps, a lot more comparison sites. There’s been a fair bit of noise and it’s not always clear from the outside who you’re actually dealing with and who’s got their own pocket in mind.
What Fairstone Actually Does
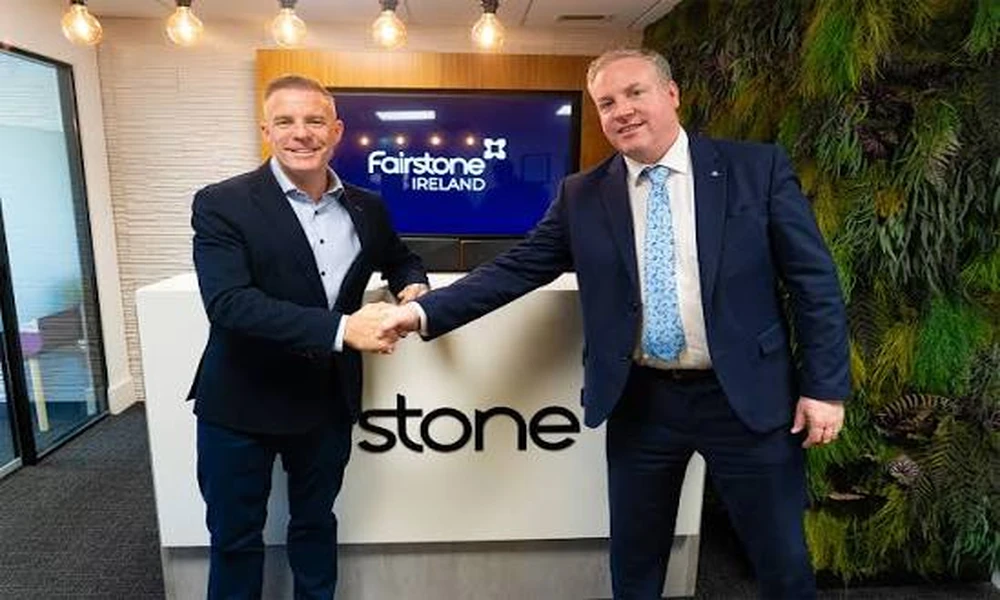
Fairstone is an independent financial planning firm here in Ireland. “Independent” is a term that’s used all the time so what does it actually mean? It means no panel of products, no-one gets a bonus for selling one fund over another. You come in and they look at your situation as it is and they tell you what they think is right – even if it’s rather boring, rather unpalatable and in fact pays them virtually nothing in commission.
Pensions, investments, life cover, income protection, general planning… they do the whole shebang. That’s a very useful range as most people’s money isn’t going to be in one pot. Take the self employed person in their 40s as an example. They’re probably looking at a PRSA, some solid income protection in the event of sickness and what their life cover actually pays out. If you’re then going to get advice on each of those individual things from a different provider who all have their own agenda then it very quickly becomes a right mess.
Fairstone is also linked to askpaul which will be very much a name that will be known to a lot of people in Ireland through Paul Merriman’s financial education work. They therefore occupy a rather unusual position in the market as a regulated advice business which also has the genuine pedigree of being involved in financial education as well as advice.
The Pension Problem Nobody Wants to Look At
Pensions are probably the area where the bulk of Irish adults are most at risk. Auto enrolment has been the topic of discussion for years and is finally, very slowly, getting underway. A huge number of people in the private sector have either not saved enough, have lost the pension from a prior job (or both). Nobody likes opening that drawer. A lot of people just leave it shut.
Go to a proper advisor and you’ll get it absolutely straight. You may well be behind where you’d like to be. The question then is what can actually be done about it from here? That’s a very different proposition to opening up an app which gives you a projection based on a set of assumptions that you never actually chose and which you can’t really challenge in any way.
Tax relief on pension contributions is still one of the biggest deals of all for anyone with earned income in Ireland and it’s still massively underused. Depending on your age and your income, a large proportion of your earnings can go into a pension with relief at your marginal rate of tax. If you’re on the 40% rate of tax, that makes a huge difference to the actual cost of the contributions. You’ll have probably heard of it in the broadest terms, virtually all of us have, but very few of us have actually done the arithmetic on our own pay.
So when is independent advice worth paying for?
It’s fair to ask whether it’s worth paying for advice at all and the answer to that really depends on where you are in life. A 20-something with just one workplace pension and nothing else in the first instance is probably not going to need a full financial plan. It’s a very different matter when you’re about to make a major decision – be that buying a house, changing career, planning for retirement in your 50s or simply sitting on a lump sum and wanting to do something sensible with it. In those circumstances proper advice will tend to pay for itself fairly quickly.
Complexity is the other area where it actually earns its keep. You’re self employed, you’ve lived or worked abroad, your income comes in from a variety of different streams, you’ve inherited something and not quite sure what to do with it? The number of things that can go wrong without you even realising is enormous.
Ireland has never been particularly good at talking about money. You can have a long chat about house prices and then be absolutely silent when you’re asked if your pension is in any sort of shape at all. That’s starting to change, slowly, and in part that’s down to companies like Fairstone who have made the effort to make financial planning feel less like you’ve been summoned to the headmaster’s office and more like a normal, sensible conversation. That’s absolutely true.